.svg)


 English
 العربية

What Makes You Ready to Buy a Home in the UAE? A Practical Checklist
- December 31, 2025
- /
- Buyer and Seller Guides
_1767169496_05b85815.webp)
Purchasing a property in the UAE involves more than just locating the perfect home; it also requires demonstrating to lenders and sellers that you are genuinely prepared. Use this checklist to evaluate your finances, documents, and timelines before making an offer. For additional property insights, explore our OIA blog.
1) Your income and debts fit the UAE affordability rule
Banks evaluate your Debt-Burden Ratio (DBR), which is the percentage of your monthly income that goes toward all your debts. In the UAE, the DBR cannot exceed 50%, and lenders must adhere to this limit when considering new mortgage applications. If your current obligations, such as credit cards, loans, and car finance, are already close to 50%, consider reducing your balances or closing unused credit limits before applying for a mortgage.
Tip: Request an estimate of your DBR during the pre-approval process, and maintain stable credit behaviour until the transfer is complete.
2) Your credit score and report are in shape
The Al Etihad Credit Bureau (AECB) score ranges from 300 to 900, with higher scores indicating better offers and easier approvals. You can purchase your score or report directly from AECB to check for any late payments or high credit utilization that may negatively impact your rates.
To utilize this information: If your score is low, ask your bank how much improvement would enhance your interest rate or increase your approval amount. Then, adjust your debt usage and repayment history accordingly. Additionally, banks provide valuable guidance on the importance of credit scores.
3) You have the down payment, and understand LTV limits
UAE mortgages are regulated by the Central Bank, which establishes maximum Loan-to-Value (LTV) ratios based on the buyer's profile, the property value, and whether the unit is completed or still off-plan. Here’s what that means in practice:
- For many expatriates purchasing their first home valued at up to AED 5 million, banks may offer an LTV of up to approximately 80% (meaning a down payment of about 20%), depending on their policies.
- UAE nationals can access higher LTVs for their first homes, with the regulations allowing for up to 85% LTV for properties valued at AED 5 million or less, under certain conditions.
- When it comes to off-plan mortgages, the LTV is more conservative, with a maximum cap of 50% at the time of issuance.
Always verify the specific product rules with your lender.
Why is this important? If your desired down payment is tight, consider adjusting your budget or utilizing a developer's payment plan for off-plan projects, and then look into refinancing later.
4) Your timeline fits the maximum mortgage term
In the UAE, mortgage regulations limit the term to a maximum of 25 years. There are also age restrictions regarding the final payment: non-nationals typically must be no older than 65, while UAE nationals can be up to 70 years old, depending on their employment type. It's important to align the mortgage term with your cash flow and career trajectory. Longer terms result in lower monthly instalments but increase the overall cost of the loan.
5) You’ve budgeted the actual “all-in” cost to buy
In addition to the down payment, it's important to budget for government and administrative fees:
Dubai: A transfer fee of 4% of the purchase price is charged by the Dubai Land Department (DLD), along with trustee/admin fees and a No Objection Certificate (NOC) fee.
Abu Dhabi: The registration fee is generally 2%, although this can vary based on local schedules and incentives. Additionally, there may be applicable administrative and title issuance fees. It’s always a good idea to confirm the latest fee schedule.
Don’t forget to include costs for property valuation, bank processing, insurance, and any agency fees in your budget. For more details on these line items and to allow for unexpected expenses, visit our OIA blog.
6) You’re pre-approved, and your documents are ready
A strong pre-approval indicates to sellers and agents that you are a serious buyer. You should expect to provide identification, proof of residency, and income verification (such as a salary certificate or trade license), along with bank statements and a credit check. Major banks outline the typical documentation required and recommend starting the pre-approval process before viewing homes.
If you are abroad, several banks cater to non-resident buyers with specific policies and lower loan-to-value ratios (LTVs). Make sure to check your eligibility and the necessary documentation before you start shortlisting properties.
7) You understand title transfer and process basics
Each emirate manages property registration through its official portal or via trustee offices. In Dubai, property transfers are handled by authorized Real Estate Trustees following the procedures set by the Dubai Land Department (DLD). In Abu Dhabi, registrations are processed through the Department of Municipalities and Transport (DMT) via TAMM workflows, which include published fee schedules. Understanding the steps in advance helps prevent any last-minute surprises.
8) Your purchase plan matches your visa goals :
Purchasing property valued at AED 2 million or more may qualify you for a 10-year Golden Visa under the real estate category, provided you meet the eligibility criteria, including paid-up thresholds for mortgaged properties. Always verify the current rules before relying on visa outcomes.
9) You’ve stress-tested repayments
EIBOR-linked mortgages can fluctuate over time. It’s advisable to model a scenario where rates increase by 1% to ensure you’re prepared for potential rises. Many lenders provide calculators that illustrate how fixed, variable, or hybrid mortgage structures perform over the term. For a customized illustration, check your bank’s product pages and consult with an advisor.
10) You’re clear on property type, location, purpose and holding period
Align the area with your goal (end-use or investment) and holding period. Use these guidelines, then explore further through the linked resources.
Yas Island: family lifestyle + year-round demand
Great for active families and investors who value entertainment anchors and steady rental interest.
Read next: Aldar Ready Homes on Yas Island
Saadiyat Island: culture + beach prestige
Blue-chip address near museums and coastline; suits end-users seeking quiet luxury and long-term holders.
Read next: Saadiyat Cultural District Guide
Al Reem Island: urban convenience + yields
High-rise living close to CBD; popular with professionals and yield-focused buyers.
Read next: Al Reem Island, Complete Community Guide
Al Raha Beach: waterfront communities
Family-friendly promenades and marinas; balanced for end-use and long-let investors.
Read next: Everything You Need to Know Before You Move to Al Raha Beach.
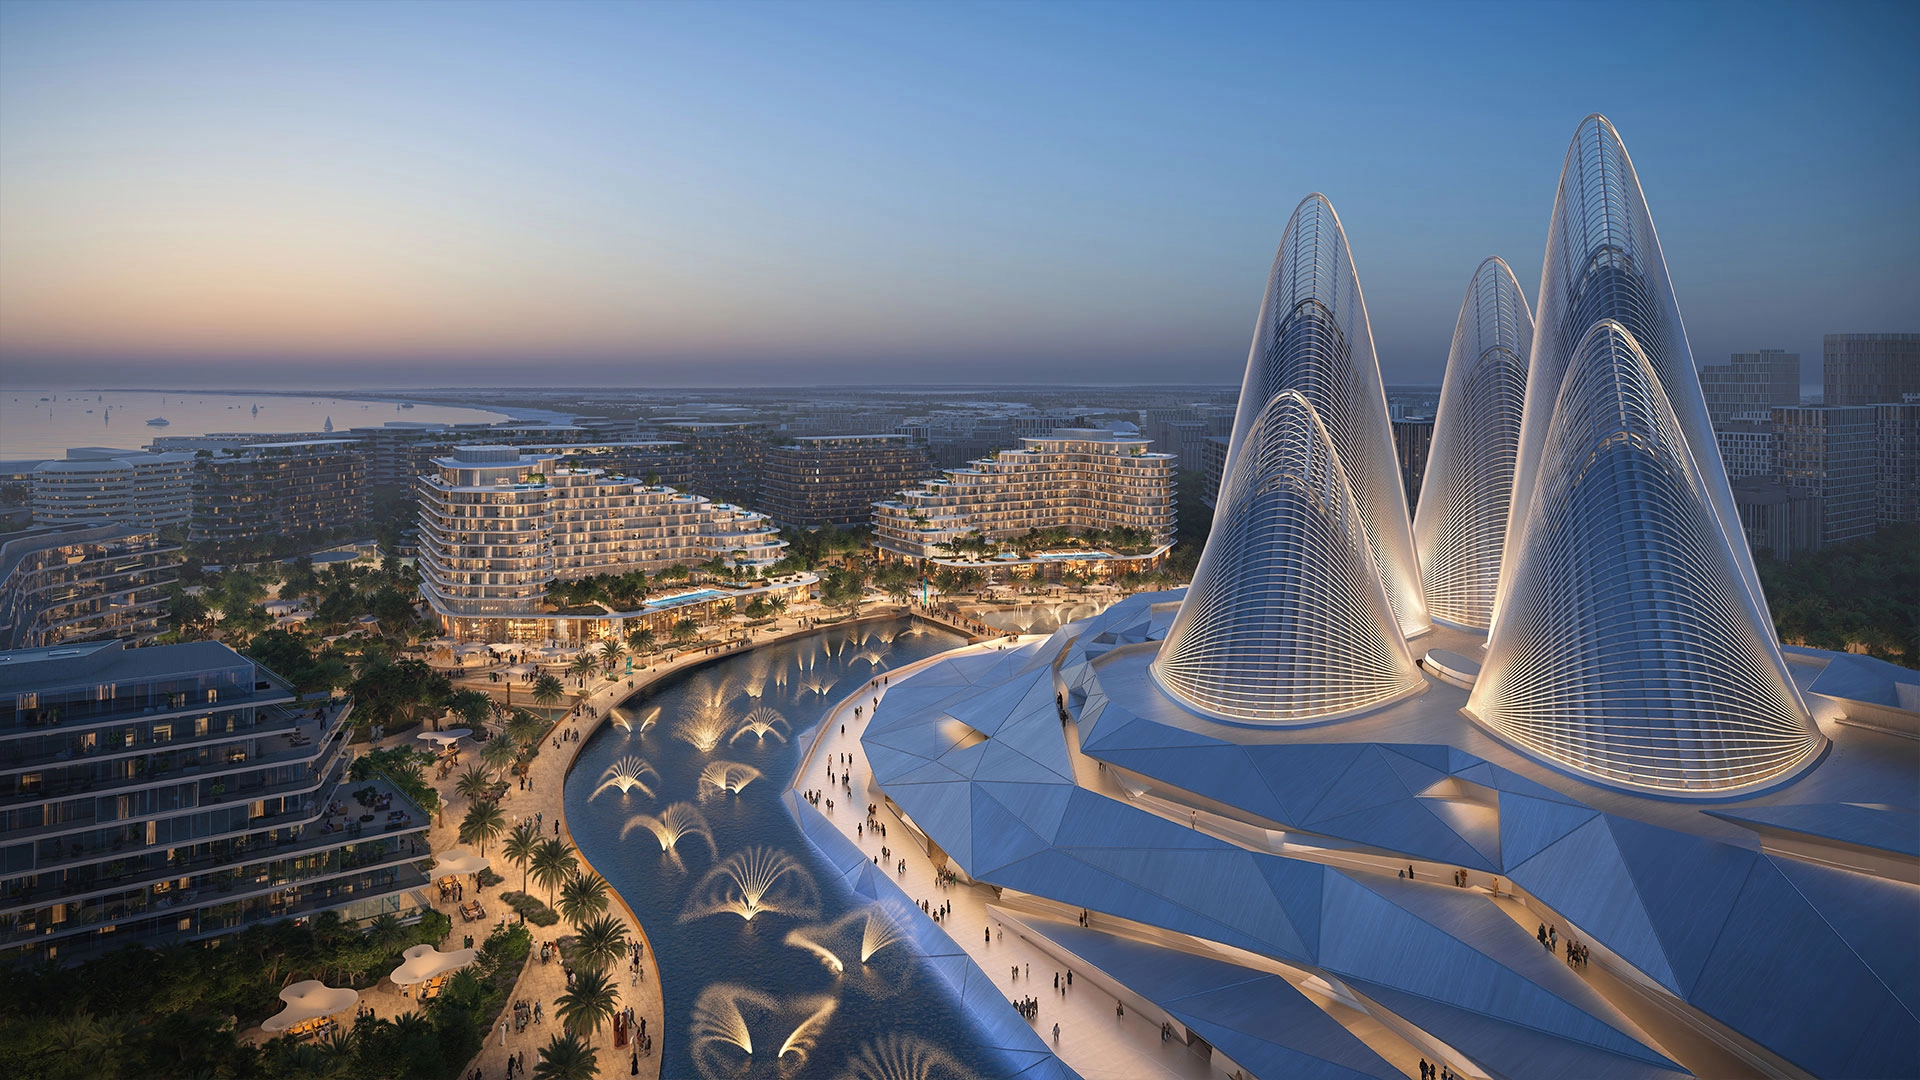
Fahid Island: next-gen waterfront luxury
Low-carbon, high-end island living; early investors target staged payment plans and capital growth.
Read next: Fahid Island Investor Guide 2025
OIA Properties: your advisor and execution team
At OIA, we pair grounded market knowledge with bank-ready execution. We will:
Map your affordability and pre-approval steps, then translate that into a smart viewing plan.
Provide area and project comparisons with fee and yield context to ensure decisions are data-driven.
Manage the process end-to-end: offers, NOC, valuation, transfer, and handover checklists.
Ready to move forward? Contact us now
